Home Insurance, coverage types
Renters Insurance: What It Covers, What It Costs, and How to Choose It
Your landlord's policy covers the building, not you. A renters policy fills that gap for about $14 a month on average. Here is what it covers, what it leaves out, and how to pick the right limits.
- By
- Ella H.
- Published
- Updated
- Reading time
- 15 min read
Key takeaways
- Your landlord's insurance covers the building only. It does not cover your belongings, your liability, or the cost of living elsewhere after a loss.
- A standard renters policy, the HO-4 form, covers personal property, personal liability, and additional living expenses.
- The average HO-4 premium was $173 a year in 2023, according to NAIC data reported by the Insurance Information Institute.
- Liability coverage usually starts at about $100,000, and experts recommend at least $300,000 if you can afford it.
- Renters insurance does not cover floods, earthquakes, the building itself, or a roommate's belongings unless that roommate is named on the policy.
In this guide
Renters insurance is the policy that protects everything a landlord's policy does not: your belongings, your liability, and the cost of living somewhere else while your home is repaired after a covered loss. If you rent an apartment, a house, or a room, this is the policy written for you. The standard form is called HO-4, and it is one of the cheapest insurance products in the United States. The average HO-4 premium was $173 a year in 2023, according to data from the National Association of Insurance Commissioners (NAIC) reported by the Insurance Information Institute (III) 1. That is about $14 a month for coverage that can replace a whole apartment's worth of belongings and defend you in a lawsuit.
The gap it fills is bigger than most renters think. A fire, a burst pipe, or a break-in can destroy thousands of dollars of things in a single afternoon, and a guest who slips in your kitchen can turn into a liability claim that costs far more. Nearly half of renter households spent at least 30% of their income on rent and utilities in 2024, according to Census data cited by the III, which means most renters have little room to absorb a sudden loss on their own 1. Renters insurance exists for exactly that moment.
Your landlord's insurance does not cover you
This is the single most common misunderstanding about renting, and it is worth stating plainly: your landlord's insurance covers the building, not you. If a fire damages the apartment, the landlord's policy pays to repair the walls, the roof, and the landlord's own fixtures. It does not pay to replace your sofa, your laptop, or your clothes. It does not pay your hotel bill while the apartment is uninhabitable. And it does not defend you if a guest is injured inside your home.
The confusion is understandable. Renters often assume that because someone insures the property, they are covered by extension. They are not. The landlord's policy names the landlord as the insured, and the renter is not a party to that contract. Your belongings are your responsibility, and so is your liability for what happens inside the space you rent.
A security deposit does not fill the gap either. A deposit is the landlord's money, held against damage to the unit or unpaid rent, and returned at move-out if the place is in good shape. It protects the landlord, not the renter. It pays nothing if your things burn, nothing if your belongings are stolen, and nothing if a guest is hurt. Thinking of a deposit as a substitute for insurance is one of the most expensive mistakes a renter can make, because it feels like protection while offering none.
No federal law requires renters insurance, but landlords can require it in the lease, and more of them do every year. A typical lease requirement sets a minimum liability limit and asks for proof of coverage before you move in. Some landlords also ask to be named as an "additional interest" on the policy, which means the insurer tells them if the policy lapses or is cancelled. If your lease has such a clause, you need a policy in force on move-in day, not after the first month. Read the lease before you sign, and check the exact liability limit it asks for, because a policy that meets one landlord's requirement may fall short of another's.
What renters insurance covers
A standard HO-4 policy covers three things: your personal property, your personal liability, and your additional living expenses. The property part works on a named-perils basis, which means it covers only the causes of loss listed in the policy. Those causes typically include fire and lightning, windstorm and hail, smoke, theft, vandalism, falling objects, the weight of ice and snow, accidental discharge of water from a burst pipe or a broken appliance, and damage from a vehicle or aircraft. If the cause is not on the list, the policy does not pay.
Personal property means the movable things you own: furniture, clothing, electronics, kitchenware, books, and anything else inside the home. It also covers belongings you keep outside the home, usually up to 10% of your personal-property limit. If your property limit is $25,000, for example, about $2,500 of coverage follows your things when they are away from home, such as a laptop stolen from your car or luggage lost while traveling 2.
Personal liability is the part renters most often underestimate. If a guest trips on a rug in your apartment and breaks a wrist, or your dog bites a neighbor in the hallway, or your child throws a ball through a neighbor's window, liability coverage pays the medical bills and legal costs, up to your limit, and provides a lawyer to defend you. Liability limits usually start at about $100,000, and experts recommend at least $300,000 if you can afford it 2. The difference in premium between $100,000 and $300,000 is usually small, and the extra protection is large, because a single serious injury claim can easily pass $100,000.
Medical payments to others is a smaller, separate coverage that pays small medical bills for guests hurt on your property regardless of who was at fault, usually without a lawsuit. It typically runs from $1,000 to $5,000 2. It is meant for the quick, no-fault cases: a guest who cuts a hand on a broken glass and needs stitches, for instance.
Additional living expenses, often called loss of use, pays the extra cost of living somewhere else while your home is uninhabitable after a covered loss: a hotel or a short-term rental, restaurant meals above what you would normally spend on groceries, laundry, and similar costs. If a fire forces you out of your apartment for two months, this coverage is what keeps you from paying rent on a home you cannot live in plus a hotel on top of it.
| Coverage | What it pays for | Typical limit |
|---|---|---|
| Personal property | Your belongings, at home and away | You choose the limit; off-premises typically 10% of it |
| Personal liability | Injuries and property damage you cause to others, plus legal defense | Starts at about $100,000; $300,000 recommended |
| Medical payments to others | Small medical bills for guests, no fault needed | Typically $1,000–$5,000 |
| Additional living expenses | Hotel, rental, and extra food costs while you cannot live at home | Set as part of the policy |
One more option is worth knowing about: umbrella liability. An umbrella policy sits on top of your renters liability and adds an extra $1 million of coverage, typically for $200 to $350 a year 2. It is worth considering if you have savings or future income to protect, because it is cheap protection against a rare but ruinous claim.
What renters insurance does not cover
A renters policy has clear exclusions, and knowing them before a loss matters more than knowing them after one. Floods are not covered. Earthquakes are not covered. The building itself is not covered, because you do not own it. Vehicles are not covered, because they belong on an auto policy. And your roommate's belongings are not covered unless that roommate is named on the policy 2.
Flood is the exclusion that surprises the most people, because water damage from a burst pipe is covered while water damage from a flood is not. The difference is the source of the water. A pipe that bursts inside your home is a covered peril. Rising water from a storm, a overflowing river, or heavy rain that enters from outside is a flood, and it needs a separate flood policy. If you live on a ground floor, near a river, or in an area with a history of flash flooding, ask about flood coverage separately rather than assuming your renters policy handles it.
Earthquake coverage is a separate add-on in the states where it is offered, and it is usually not included in a standard HO-4. If you rent in California, the Pacific Northwest, or another earthquake-prone area, check whether your insurer offers it and what it costs. The same logic applies to other regional risks: check what your policy excludes in your area, not just what it covers.
Damage that builds up slowly is also excluded. A slow leak that rots a floor over months, mold from long-term dampness, and wear and tear on your belongings are maintenance problems, not sudden losses, and the policy does not pay for them. Neither does it pay for damage you cause on purpose, or for business property beyond a small limit if you run a business from home. If you work from your apartment with expensive equipment, ask your insurer whether your business property needs a separate endorsement or a business policy.
Finally, the standard limits on valuables deserve attention. Jewelry, watches, and furs usually have a standard limit of about $1,500 for theft, which means an engagement ring or a watch worth more than that is only partly covered 2. If you own valuables above the standard limit, you can add a floater or scheduled personal property endorsement that covers the specific item for its full appraised value, usually including loss and mysterious disappearance, which the standard policy does not cover.
How much renters insurance costs
The honest answer starts with the number that comes from actual policies, not from quotes. The average HO-4 premium in the United States was $173 a year in 2023, based on NAIC data reported by the III 1. That is up only 1.2% from $171 in 2022, and it is lower than the $190 average recorded in 2014. For comparison, the average homeowners premium in the same data was $1,737 a year, up 10.7% from 2022, which makes renters insurance roughly a tenth of the cost of insuring a house 1.
You will see other numbers online, and it helps to know why they differ. Some sites quote $165 a year or $22 a month, but those are quote samples for a specific profile, such as $30,000 of property coverage, $100,000 of liability, and a $500 deductible, not the average of what renters actually paid. Others claim $18 to $25 a month and attribute the figure to the III or the NAIC, but no such figure appears on the III or NAIC pages. The $173 figure is the average premium on real HO-4 policies, and it is the number to trust.
Prices vary by state. The highest average premiums in 2023 were in Mississippi at $263, Louisiana at $250, and Oklahoma at $220. The lowest were in South Dakota at $125, North Dakota at $127, and Wisconsin at $133 1. The spread reflects the same forces that drive homeowners prices: storm risk, crime rates, construction costs, and how often claims are filed. Your own premium will depend on your state and city, the amount of coverage you buy, your deductible, your claims history, and whether you bundle the policy with auto insurance.
The cost is low enough that the usual objection, that insurance is an extra bill, does not hold up well. At about $14 a month on average, a renters policy costs less than most subscription services, and it protects everything you own. The risk is not the premium. The risk is replacing a whole apartment's contents out of pocket after a fire or a burglary, which can run into the tens of thousands of dollars.
How to pick your limits
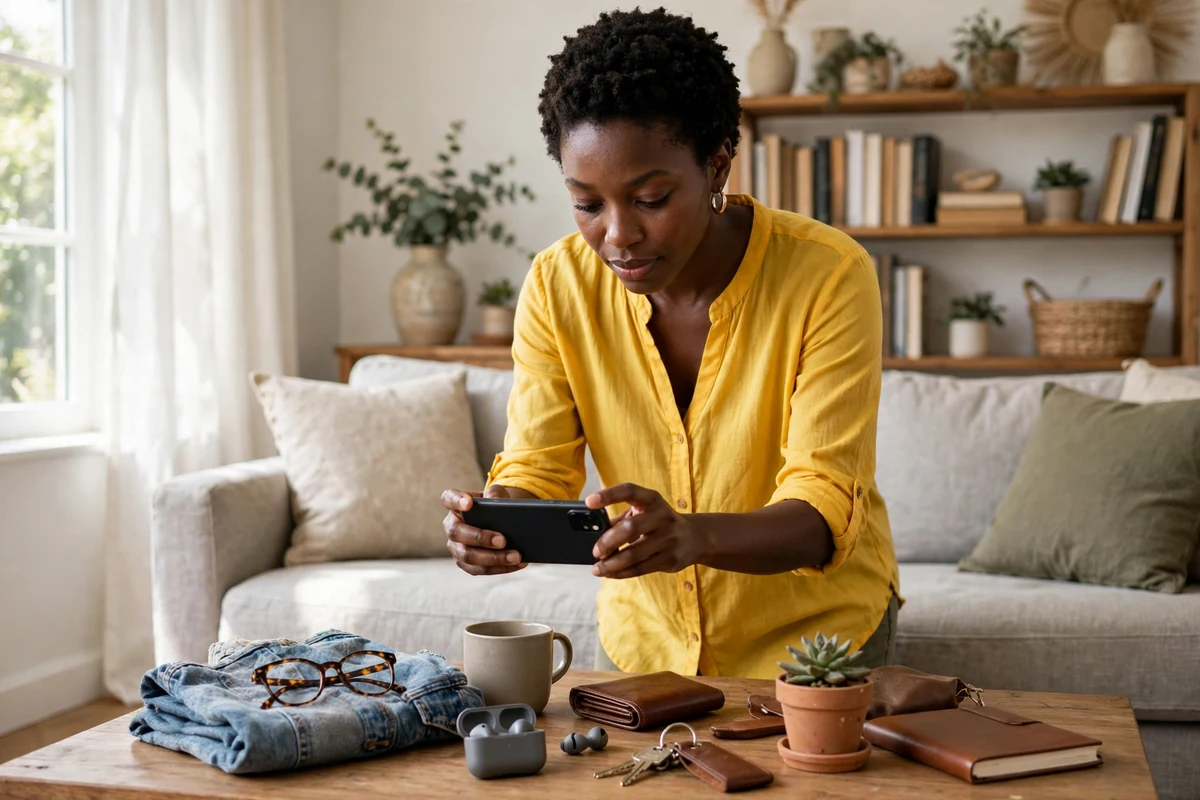
Choosing limits starts with a home inventory, and the III's core advice is to make one before you buy. Walk through your home room by room and list what you own, with a rough replacement cost for each item. Most people underestimate what they own by a wide margin. A bedroom alone can hold a bed, a mattress, a dresser, clothes, shoes, a television, and a laptop. A kitchen holds appliances, cookware, and dishes. Add it up across a whole apartment and the total is usually far higher than the first guess. Your personal-property limit should equal the cost of replacing everything, not the cost of the few big items you remember first.
Once you have the total, decide how the policy values your things. Actual cash value pays replacement cost minus depreciation, so a five-year-old television is worth much less than a new one. Replacement cost pays what it costs to buy a new item of like kind and quality, without subtracting depreciation, and it costs about 10% more than actual cash value coverage 2. For most renters, replacement cost is worth the extra 10%, because the point of the policy is to rebuild your life after a loss, not to hand you the depreciated value of used furniture.
Liability deserves the same deliberate choice. The default of about $100,000 is a floor, not a target, and experts recommend at least $300,000 2. If you have a dog, children, or a lifestyle that brings many guests into your home, the higher limit matters more. And if your assets or future earnings are significant, consider the umbrella policy described above, which adds $1 million of liability for $200 to $350 a year 2.
The deductible is the amount you pay out of pocket before the insurer pays anything. Raising it from $500 to $1,000 may save up to 25% off the premium 2. On a $173 average premium, that is a saving of roughly $43 a year, in exchange for paying $500 more out of pocket on a claim. Whether that trade is worth it depends on your savings: if you can comfortably cover a $1,000 deductible, the higher deductible is usually the better deal. If you cannot, keep the deductible low and pay the slightly higher premium.
Check the sublimits before you buy. The $1,500 jewelry limit, the 10% off-premises rule, and any limits on electronics, firearms, or collectibles should be on your radar. If a sublimit leaves something important underprotected, add an endorsement for that item rather than raising the whole property limit, which is usually the more expensive way to fix a narrow gap.
Roommates, students, and pets
Renters insurance gets complicated when more than one person lives in the home, and the rules are worth knowing before you sign. A roommate is not automatically covered by your policy. Your policy covers your belongings and the belongings of people named on it. A roommate who is not named needs a separate policy, or needs to be added to yours if the insurer allows it. Some insurers allow joint coverage for unmarried couples living together, but the rules vary by state and by company, so ask directly rather than assuming 2.
College students have their own wrinkle. A student living in a dorm is usually covered under a parent's homeowners or renters policy, because the dorm is treated as a temporary residence. A student living off campus in an apartment usually needs a separate renters policy, because the off-campus apartment is a separate residence. If your child is heading to college, check with your insurer before move-in day, and do not assume the dorm rule follows them off campus.
Pets are covered for liability under most renters policies, which means a dog bite or a cat that scratches a guest is generally covered up to your liability limit. But some insurers exclude certain dog breeds or ask about bite history, and a policy may exclude a pet with a known history of aggression. Be honest about your pets when you buy the policy. An undisclosed pet can become a reason for a denied claim, and a bite claim is exactly the kind of loss where the liability limit matters.
How to buy a policy and file a claim
Buying a renters policy is usually quick. You can buy from the same insurer that covers your car, which often earns a bundling discount, or from a standalone renters insurer. You will need your address, the amount of property coverage you want, your liability limit, and your deductible choice. Many insurers can issue a policy the same day, and the declarations page, the summary of your coverages and limits, is usually available immediately. Keep a copy somewhere you can find it after a loss, not only in the apartment itself.
If a covered loss happens, the claim process has a clear order. First, make sure everyone is safe and stop further damage if you can do so safely, for example by turning off the water after a burst pipe. Second, document the damage with photos and video before you clean up or throw anything away. Third, notify your insurer promptly and file a police report if there was a theft or a break-in. Fourth, make a list of damaged or stolen items with their approximate value and, where you have them, receipts or photos. The home inventory you made when you bought the policy becomes the most valuable document you own at this point, because it turns a stressful memory exercise into a checklist.
An adjuster will usually be assigned to review the claim, and the insurer will pay up to your coverage limit, minus your deductible. Keep receipts for any additional living expenses, such as hotel stays and meals, because those are reimbursed from your loss-of-use coverage. And keep copies of everything you send the insurer, including the claim number, the adjuster's name, and the dates of every conversation.
How to lower the cost
Renters insurance is already cheap, but a few habits can make it cheaper still. Bundling with an auto policy from the same insurer is the most common saving, and the III lists it first among renters discounts, though it gives no percentage for renters specifically 2. Safety features help too: a security system, smoke detectors, and dead-bolt locks are all listed by the III as ways renters can save 2. Age and non-smoker status can also earn a discount with some insurers.
Raising the deductible, as described above, may save up to 25% off the premium when you move from $500 to $1,000 2. Paying the premium annually instead of monthly can avoid installment fees with some insurers. And it is worth comparing quotes from at least three insurers, because premiums for the same coverage can differ widely between companies. The cheapest policy is not always the best one, though. Check the insurer's claims reputation and the exact coverages before you choose on price alone, and make sure the quote you compare has the same limits, deductible, and replacement-cost terms as the others.
Verified against the Insurance Information Institute on November 19, 2026.
The bottom line
Renters insurance is a small policy that covers a large risk. For about $173 a year on average, it replaces your belongings after a fire, a theft, or a burst pipe, defends you if someone is hurt in your home, and pays for a place to stay while your home is repaired. Your landlord's policy does none of those things. Make a home inventory, choose replacement cost coverage, set liability at $300,000 if you can, and check the sublimits on jewelry and valuables. Then read the lease, buy the policy before move-in day, and keep the declarations page where you can find it. The policy you never need costs $14 a month. The policy you need and do not have can cost everything you own.
Frequently asked questions
- Does my landlord's insurance cover my belongings?
- No. Your landlord's policy covers the building and the landlord's own property. Your furniture, clothing, electronics, and other belongings are not covered by it, and neither is your liability if someone is hurt in your apartment.
- How much does renters insurance cost?
- The average HO-4 renters policy cost $173 a year in 2023, according to NAIC data reported by the Insurance Information Institute. That works out to about $14 a month. Your own premium depends on where you live, how much coverage you buy, and your deductible.
- What does renters insurance cover?
- Three things: your personal property against named perils such as fire, theft, and burst pipes; your personal liability if you injure someone or damage their property; and additional living expenses if a covered loss makes your home unlivable.
- Does renters insurance cover floods or earthquakes?
- No. A standard renters policy excludes flood and earthquake damage. Flood coverage comes from a separate policy, usually through the National Flood Insurance Program or a private flood insurer, and earthquake coverage is a separate add-on where it is available.
- Does renters insurance cover my roommate's things?
- No, not automatically. Your policy covers your belongings and the belongings of people named on the policy. A roommate needs to be named on the policy or buy a separate one. Rules for unmarried couples living together vary by state and insurer, so ask before you assume.
- Is renters insurance required?
- No federal law requires renters insurance, but a landlord can require it in the lease, usually with a minimum liability limit and proof of coverage before you move in. Some landlords also ask to be named as an additional interest so they are told if the policy lapses.
Sources
Numbers in the text point to these publications. Links open the original source.
- Insurance Information Institute (Triple-I). Facts + Statistics: Renters insurance
- Insurance Information Institute (Triple-I). Renters Insurance
Related guides
- What Does Homeowners Insurance Cover? (And What It Does Not Cover)
A standard homeowners policy covers your dwelling, other structures, belongings, living expenses, and liability — but not floods or earthquakes.
- How Much Does Homeowners Insurance Cost? Average Rates by State
The official NAIC average HO-3 premium was $1,737 a year in 2023 data, while modeled 2026 quotes average $2,490 for $400,000 of dwelling coverage.
- What Is Homeowners Insurance and How Does It Work?
Homeowners insurance is a contract that pays to repair or rebuild your home after a covered loss and protects you if someone is hurt on your property.
This guide is general educational information, not insurance, legal or financial advice. Insurance rules and prices vary by state, company and personal circumstances. Confirm anything important with your state insurance department or a licensed professional. Read the full disclaimer.