Home Insurance, coverage types
Earthquake Insurance: What It Covers, What It Costs in 2026, and How the Deductible Really Works
Your homeowners policy does not cover the shaking — and the deductible, not the premium, is the number that decides whether a policy is worth buying.
- By
- Ella H.
- Published
- Updated
- Reading time
- 15 min read
Key takeaways
- Standard homeowners and renters insurance does not cover earthquake damage, although fire following a quake is generally covered by the homeowners policy.
- In California in 2025, the average homeowners earthquake premium was $1,440.11 a year — $1.62 per $1,000 of coverage — with only 15.24% of homeowners carrying the cover.
- The deductible is a percentage of your dwelling limit, usually 10% to 20%: a 15% deductible on a $400,000 home means $60,000 out of pocket before the policy pays anything.
- The California Earthquake Authority offers deductibles of 5%, 10%, 15%, 20% or 25%, but the 5% and 10% options are not available on homes worth over $1 million or on pre-1980 raised-foundation homes without a verified retrofit.
- Earthquake Brace + Bolt grants of up to $3,000 can pay for a retrofit, with up to $7,000 more for income-eligible households — and insurers usually will not sell a new policy for a month or two after a quake.
In this guide
- What earthquake insurance covers — and what it does not
- The deductible is the whole decision
- What it costs in 2026: the real California numbers
- Who actually needs it
- How to buy it in California
- Cheaper than a policy: retrofits and grants
- What happens if you go without it
- The bottom line
- Frequently asked questions
- Sources
If an earthquake damages your home tomorrow, your homeowners policy will almost certainly pay nothing for the shaking itself. Standard homeowners and renters insurance does not cover earthquake damage — that is the first fact to understand, and the one most homeowners get wrong 1. The same policy that pays for a fire or a burst pipe simply excludes the ground moving under your house. What it generally does cover is fire following a quake: if the shaking breaks a gas line and the house burns, the fire damage is covered by the homeowners policy, and additional living expenses are covered if that fire makes the home unlivable 1. Your car is covered too, but only under the optional comprehensive part of your auto policy 1.
That gap matters because earthquakes are not a California-only problem. 42 states are at risk of earthquake damage, according to the U.S. Geological Survey, as reported by the National Association of Insurance Commissioners 2. Yet only 11% of American homeowners had earthquake insurance, according to a Triple-I poll cited by the NAIC 2. In California — which has had 6 of the 10 costliest earthquakes in U.S. history — only 10% of residents have earthquake insurance, and only 11.3% of Washington residents were covered in 2017 2. The mismatch between the risk and the coverage is the reason this guide exists: to show what the cover costs in 2026, how the deductible really works in dollars, and what help exists if you cannot afford a policy.
What earthquake insurance covers — and what it does not
An earthquake policy typically covers direct damage from shaking only 2. That means cracks in the foundation and walls, a chimney that collapses, a home knocked off its foundation, and the belongings broken or destroyed inside. Indirect damage is handled elsewhere: fire and water damage from burst gas and water pipes are covered under a homeowners policy, and vehicle damage falls under an auto policy 2.
In California, most earthquake insurance comes from the California Earthquake Authority (CEA). You cannot buy directly from the CEA — you buy through a participating insurer, and your residential policy must be with the same company 4. The CEA's basic homeowners coverages, as described by the California Department of Insurance, are:
| Coverage | What the CEA offers |
|---|---|
| Dwelling | Limit must equal your homeowners dwelling limit |
| Personal property | $5,000 or $25,000 |
| Additional living expenses / loss of use | $1,500 to $100,000, never with a deductible |
| Building-code upgrades | Purchasable up to $30,000 |
| Emergency repairs | First $1,500 with no deductible |
Source: California Department of Insurance earthquake guide and CEA homeowners coverages 4 7.
Two details in that table deserve attention. First, the personal property limit is $5,000 or $25,000 — not the $200,000 figure that still appears in several 2026 guides. That larger limit dates to a 2016 product change and is no longer what the CEA offers. Second, loss of use has no deductible at all, and neither does the first $1,500 of emergency repairs. If a quake makes your home unlivable, the money for a hotel and meals starts immediately, even while your dwelling deductible is still unpaid. The CEA also offers a Homeowners Choice option that lets you buy dwelling-only cover and choose separate deductibles, and the personal-property deductible is waived if the dwelling deductible is met 4. Condo owners can buy loss-assessment coverage up to $100,000 4.
What the policy does not cover matters just as much. CEA exclusions include fire (covered by your homeowners policy), land such as sinkholes and erosion, vehicles, flood, tsunami, or sewer or drain backup, and generally landscaping, pools, fences, masonry, and separate buildings 4. A detached garage, a pool, or a brick fence is usually on its own — check whether your policy lists those structures at all before you assume they are covered.
The deductible is the whole decision
With earthquake insurance, the deductible is not a footnote — it is the decision. Unlike a homeowners deductible of $500 or $1,000, an earthquake deductible is a percentage of your dwelling coverage limit, and it is large. The Triple-I puts the usual range at 5% to 15% of the policy limit 1. The NAIC's consumer guide, updated March 26, 2025, says the deductible is usually 10% to 20% of the coverage limit — for example, a $200,000 home with a 10% deductible means $20,000 out of pocket 3. The CEA's menu is wider still: 5%, 10%, 15%, 20% or 25% of the dwelling limit 7 4.
Do the dollar math before you compare prices, because the percentage hides the real number. A 15% deductible on a $400,000 home is $60,000 — that is the amount you pay yourself before the insurer pays a dollar. A 20% deductible on a $300,000 dwelling is $60,000, and a 20% deductible on $150,000 of belongings is another $30,000 — $90,000 out of pocket before any payout, in a worked example published by NerdWallet 9. This is the sticker shock that drives real conversations: in a Facebook community thread in Huntington Beach in September 2025, homeowners reported premiums of around $780 a year paired with a $76,000 deductible, and others reported roughly $1,200 a year with a $48,000 deductible. The premium is the small number. The deductible is the large one.
There are two more rules that shape how the deductible works. First, separate deductibles may apply to the home, your belongings, and outside structures — so the dwelling deductible and the contents deductible are counted separately, and both must be met before those parts of the claim pay out 3. The one softening rule is the CEA's: your personal-property deductible is waived once your dwelling deductible is met 4. Second, all earthquake events in a 72-hour period are typically treated as one event, one claim, and one set of deductibles; aftershocks after 72 hours can mean a second claim with a second deductible 3. And remember that the deductible is an uninsured loss — the money comes from your savings, not from the policy — although federal disaster loans can help cover it 3.
The CEA menu also has a restriction that surprises higher-value homeowners. The 5% and 10% deductible options are not available if the home is valued over $1 million or was built before 1980 on a raised (non-slab) foundation without a verified retrofit — in those cases the lowest deductible you can buy is 15%, which is all state law requires insurers to offer 7 4. If your home falls in either group and you want a lower deductible, a retrofit is the way to unlock it — which is where the grants in a later section come in.
What it costs in 2026: the real California numbers
For years, the most-quoted earthquake insurance price on the internet was $3.54 per $1,000 of coverage, a figure still headlining pages from Hippo and ValuePenguin. That number is stale. The California Department of Insurance published a 2025 data call — edition dated July 3, 2026 — that gives the first regulator-verified statewide averages, and the real figure for homeowners is $1.62 per $1,000 of coverage, less than half the old number 5. If a guide still quotes $3.54 as the current rate, it is quoting an older, quote-based average, not what Californians actually paid.
Here are the California 2025 actuals:
| Policy type | Policies in force | Average premium per year | Cost per $1,000 of coverage | Share with cover |
|---|---|---|---|---|
| Homeowners | 922,090 | $1,440.11 | $1.62 | 15.24% |
| All residential | 1,591,648 | $956.43 | $1.70 | 12.48% |
| CEA policies | 968,479 | $964.52 | $1.57 | — |
| Non-CEA insurers | 623,169 | $943.85 | — | — |
| Renters | — | $87.27 | — | 13.30% |
| Condos | — | $538.03 | — | 14.13% |
| Mobile homes | — | $339.68 | — | 18.95% |
Source: California Department of Insurance earthquake data call, 2025 experience year 5.
Three things stand out in that table. First, the take-up rate for homeowners is 15.24% of the state's 6,052,334 homeowners policies — higher than the often-quoted 10% figure, but still meaning roughly six in seven California homeowners have no earthquake cover at all 5. Second, the CEA wrote 968,479 residential earthquake policies at an average of $964.52 across all its policy types 5. Third, renters pay very little — $87.27 a year on average — because a renters earthquake policy covers belongings only, not the building 5.
Quote samples tell a different, wider story than the statewide average, because price depends so heavily on location, soil, home age, and construction. NerdWallet's guide, updated May 6, 2026, collected sample quotes from State Farm, GeoVera, and the CEA: a 1,200-square-foot home in Los Angeles ranged from $1,075 to $7,725 a year; a 2,600-square-foot home in Memphis, Tennessee, from $982 to $1,542; a 3,000-square-foot home in Portland, Oregon, from $523 to $2,327; and a 1,900-square-foot home in Tacoma, Washington, from $354 to $1,509. The lowest quote they found was $85 a year for a Los Angeles renter with $25,000 of personal-property cover. Deductibles in their sample ranged from 2.5% to 25% 9. The lesson is the same as with the deductible: never judge a policy by one quoted number. Get quotes for the same home, the same limits, and the same deductible, and compare the whole package.
One discount is worth asking about. Older homes may qualify for a retrofit discount of up to 25% if the home has been properly retrofitted 4. That discount, plus the lower deductible a retrofit can unlock, is often worth more than the retrofit itself costs after grants — see the grants section below.
The market is also big and shifting. U.S. earthquake direct premiums written in 2024 totalled $6,330,766,000, with California at $3,582,421,000, Washington at $463,939,000, Oregon at $206,864,000, and Missouri at $154,668,000. The top writer in 2024 was the CEA at $882,827,000, a 14.6% market share. Net premiums written fell 8.0% in 2025 to $3,434,613,000 11. And the costliest U.S. earthquakes on record, inflation-adjusted to 2024 dollars, were the 1994 Northridge quake at $33,035 million, the 1906 San Francisco quake at $8,507 million, and the 1989 Loma Prieta quake at $2,413 million 11.
Who actually needs it
The risk map is wider than most people think. The USGS's current hazard model is the 2023 50-state National Seismic Hazard Model, with the map released January 10, 2024 10. Seismic hazard is the probability of ground motion in an area, and the model uses past faults and earthquakes, how seismic waves behave, and near-surface ground conditions 10. The best way to check your own risk is the USGS state-by-state hazard pages, weighing proximity to active faults, seismic history, time since the last quake, and your building's construction, foundation, and materials 10.
Three regions outside California deserve attention. The New Madrid Seismic Zone, centred on Missouri, Tennessee, Kentucky, and Illinois, carries a 7–10% chance of a magnitude 7.5 or greater earthquake over the next 50 years, and a 25–40% chance of a magnitude 6 or greater in the same period 2. Yet coverage in the New Madrid region of Missouri fell from 60.2% in 2000 to 11.4% in 2021 2. The Cascadia region in Washington and Oregon is the other major risk, and Alaska has its own high-hazard zones. And in the western United States, over 37% of residents report having purchased earthquake coverage, according to a 2023 Triple-I and Munich Re survey — almost three times the rate in other regions 11.
The honest way to decide is to weigh three things: your USGS hazard level, what your home is worth and how it is built, and whether you could pay the deductible from savings. A newer home on a slab foundation in a low-hazard area is a different decision from a pre-1980 home on a raised foundation near a fault. If the deductible alone would wipe out your savings, a lower-deductible policy — or a retrofit that unlocks one — is worth pricing before you decide the cover is unaffordable.
How to buy it in California
California law gives you a right that many homeowners never use. A homeowners insurer must offer earthquake insurance every other year, in writing, stating the limits, deductible, and premium — and you have 30 days to accept. If you do not reply, that counts as declining 4. Earthquake insurance is not required in California, even if you have a mortgage 4. But the offer is real, it arrives on a schedule, and it is the simplest way to see your own price: the offer letter states your premium for a stated deductible, and you can compare it with quotes from other participating insurers.
A few practical rules govern the purchase. Your CEA dwelling limit must equal your homeowners dwelling limit — you cannot underinsure the structure on the earthquake policy while fully insuring it on the homeowners policy 7. You buy through a participating insurer, not directly from the CEA, and your residential policy must be with the same company 4. And timing matters in both directions: insurers typically will not sell new policies for a month or two after a quake 9, so buying after the ground shakes is usually impossible. The time to buy is before the event, not after it.
Claims have a deadline too. An insurer can deny claims not reported within one year of the inception of the loss 4. After a quake, document the damage with photos and video before you clean up, keep every receipt, and report the claim promptly — a year sounds generous until the aftershocks, the inspections, and the repairs eat it away.
Cheaper than a policy: retrofits and grants
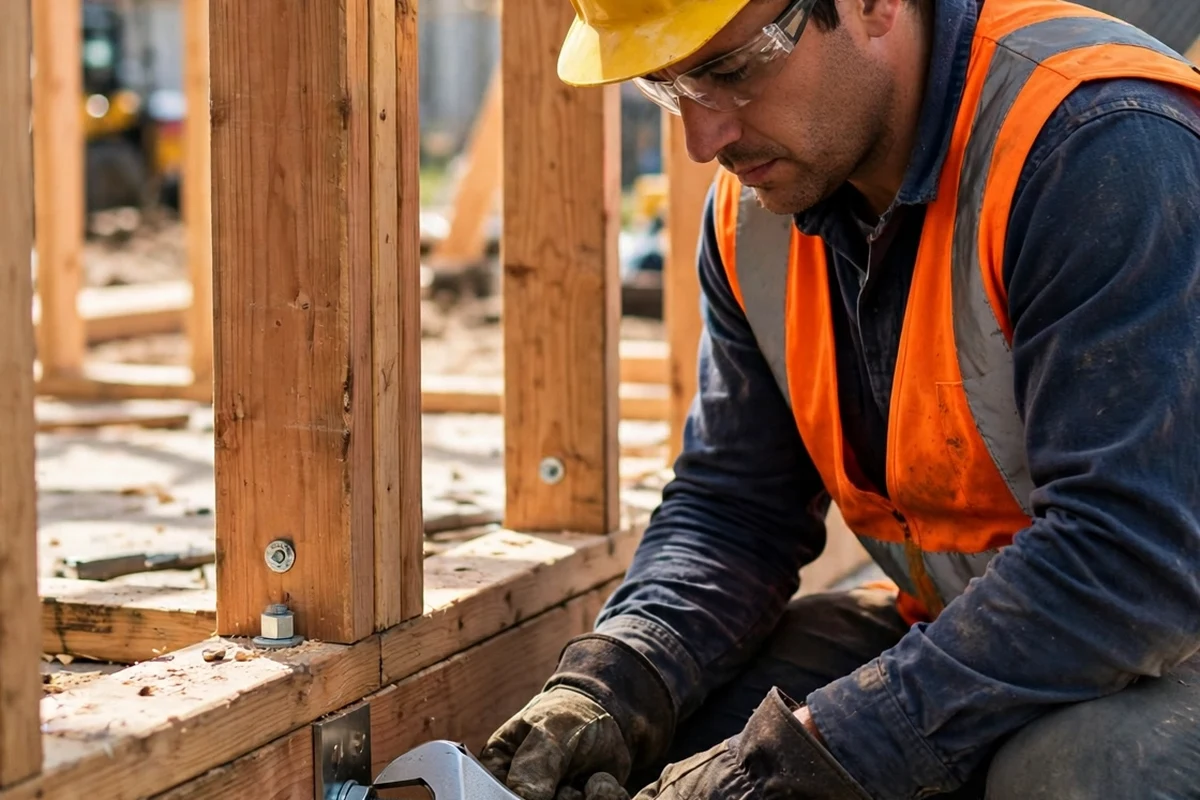
The most cost-effective earthquake spending may not be a policy at all — it may be strengthening the house. A retrofit bolts the home to its foundation and braces the cripple walls, and it can cut both your premium and your deductible. Older homes may qualify for a discount of up to 25% if properly retrofitted 4, and a verified retrofit is what unlocks the CEA's 5% and 10% deductibles for pre-1980 raised-foundation homes 7.
The Earthquake Brace + Bolt (EBB) program helps pay for that work. It offers grants of up to $3,000 toward a code-compliant retrofit of a wood-framed, pre-1980 home with a raised foundation. A typical retrofit costs $3,000 to $7,000, the work often takes 1 to 3 days, and the program covers over 1,100 high-hazard ZIP codes as of January 15, 2025. Supplemental grants may pay up to 100% of the retrofit cost for income-eligible households 8. The 2025 application round ran from August 20 to October 1, 2025, was expanded for the first time to rental and non-owner-occupied properties, and carried more than $20 million in funding; more than 32,500 homeowners have been helped since the program launched in 2013 6.
The supplemental grant is worth a careful read. The California Department of Insurance's September 4, 2025 release says supplemental grants pay up to $7,000 for income-eligible households 6. The income limit itself is stated differently in different sources, so this guide will not publish a single threshold number: the limit changes by year, and you should check the current figure when you apply. Retrofitting itself costs about $3,500 to $8,700, according to HomeAdvisor figures cited by NerdWallet 9 — in the same range as the EBB figures, which means a grant can cover a large share of the work, and sometimes all of it.
What happens if you go without it
The federal safety net is much thinner than most people assume. NerdWallet reports that the average FEMA individual-household grant after an earthquake was $4,341 for the period from October 2002 to March 2024, and that SBA low-interest loans go up to $500,000 — but a loan must be repaid 9. Those two figures come from NerdWallet's reporting of FEMA and SBA data, not from the agencies' own pages, so treat them as reported figures rather than official tallies. The point they make is the same one the California Department of Insurance makes: grants are only for people who do not qualify for loans, and the main federal help after a quake is a loan you pay back, not a grant that rebuilds your home.
That is why the decision deserves real thought rather than a shrug. A $4,341 grant does not repair a cracked foundation. A $500,000 loan is debt, taken on at the worst possible moment. An earthquake policy with a 15% deductible is also a large out-of-pocket cost — $60,000 on a $400,000 home — but it caps the loss at that number instead of leaving the whole repair bill on you. And a retrofit, partly paid for by a grant, can reduce the damage in the first place. The three options are not alternatives to each other: many homeowners combine a retrofit with a policy, using the retrofit to lower the premium and the deductible, and the policy to cover the damage that remains.
Verified against the California Department of Insurance earthquake guide and its 2025 earthquake data call, the California Earthquake Authority homeowners coverages, the NAIC consumer guide on earthquake insurance, Triple-I earthquake facts, and the U.S. Geological Survey seismic hazard pages on November 22, 2026.
The bottom line
Your homeowners policy does not cover earthquake damage — only fire that follows a quake, and only up to the limits you already carry. In California in 2025, the average homeowners earthquake premium was $1,440.11 a year, or $1.62 per $1,000 of coverage, and only 15.24% of homeowners carried the cover. The number that matters most is the deductible: 10% to 20% is typical, and 15% of a $400,000 home is $60,000 out of your pocket before the policy pays anything. If you live in California, your insurer must offer you earthquake cover every other year in writing, and you have 30 days to accept — read that offer when it arrives, do the dollar math on the deductible, and compare it with a retrofit grant before you decline. And do not wait for the ground to shake: insurers usually stop selling new policies for a month or two after a quake, and by then the decision has already been made for you.
Frequently asked questions
- Does homeowners insurance cover earthquake damage?
- No. A standard homeowners or renters policy does not cover damage from an earthquake. Fire following an earthquake is generally covered by the homeowners policy, and cars are covered under the optional comprehensive part of an auto policy. Earthquake damage needs a separate earthquake policy or an endorsement.
- How much does earthquake insurance cost in California?
- According to the California Department of Insurance's 2025 data, the average homeowners earthquake premium was $1,440.11 a year, or $1.62 per $1,000 of coverage. Renters paid $87.27 a year on average, condo owners $538.03, and mobile home owners $339.68. Prices vary widely by location, home age, construction, and deductible.
- How does an earthquake insurance deductible work?
- It is a percentage of your dwelling coverage limit, not a flat dollar amount. The CEA offers 5%, 10%, 15%, 20% or 25%. A 15% deductible on a $400,000 dwelling limit means you pay the first $60,000 of repairs yourself. Separate deductibles can apply to the home, your belongings, and outside structures.
- What is the California Earthquake Authority?
- The CEA provides most earthquake insurance in California, but you cannot buy directly from it. You buy through a participating insurer, and your residential policy must be with the same company. Its dwelling limit must equal your homeowners dwelling limit, and it offers personal property cover of $5,000 or $25,000, loss of use of $1,500 to $100,000, and building-code upgrade cover up to $30,000.
- Is earthquake insurance required in California?
- No, it is not required, even if you have a mortgage. California law does require a homeowners insurer to offer earthquake insurance every other year, in writing, stating the limits, deductible, and premium, and you have 30 days to accept. If you do not reply, that counts as declining.
- What is an Earthquake Brace + Bolt grant?
- It is a grant of up to $3,000 toward a code-compliant retrofit of a wood-framed, pre-1980 home with a raised foundation. A typical retrofit costs $3,000 to $7,000 and takes 1 to 3 days. Supplemental grants of up to $7,000 are available for income-eligible households, and the income limit changes by year, so check it when you apply.
Sources
Numbers in the text point to these publications. Links open the original source.
- Insurance Information Institute (Triple-I). Earthquake insurance for homeowners
- National Association of Insurance Commissioners (NAIC). Insurance Topics: Earthquake Insurance (last updated 4/16/2025)
- National Association of Insurance Commissioners (NAIC). Understanding Earthquake Deductibles (updated 2025-03-26)
- California Department of Insurance. Earthquake Insurance (consumer guide, revised April 25, 2024)
- California Department of Insurance. Earthquake Premium and Policy Count Data Call: Summary of 2025 Residential Totals (edition 7/03/2026)
- California Department of Insurance. Earthquake Brace & Bolt Grant Program Opens for 2025 Applications — Now Expanded to Rental Properties (Sept 4, 2025)
- California Earthquake Authority (CEA). CEA Homeowners Coverage & Deductibles
- California Residential Mitigation Program (CRMP). Frequently Asked Questions (FAQs) — Earthquake Retrofit & Seismic Mitigation
- NerdWallet. Earthquake Insurance: What's Covered, and Is It Worth It? (updated May 6, 2026)
- U.S. Geological Survey (USGS). What are the earthquake hazards/risks where I live?
- Insurance Information Institute (Triple-I). Facts + Statistics: Earthquakes and tsunamis
Related guides
- What Does Homeowners Insurance Cover? (And What It Does Not Cover)
A standard homeowners policy covers your dwelling, other structures, belongings, living expenses, and liability — but not floods or earthquakes.
- Flood Insurance NFIP Guide: What the National Flood Insurance Program Covers, What It Costs, and What It Does Not Cover
A standard homeowners policy does not cover flood damage. This guide explains NFIP limits, the 2026 average cost, the 30-day wait, and what NFIP does not cover.
- Homeowners Insurance Deductible: Flat vs Percentage, and How It Changes Your Premium
What you pay before your insurer pays. Flat vs percentage deductibles, hurricane deductibles in 19 states, and how raising yours changes your premium.
This guide is general educational information, not insurance, legal or financial advice. Insurance rules and prices vary by state, company and personal circumstances. Confirm anything important with your state insurance department or a licensed professional. Read the full disclaimer.